Demystifying Card Networks: How GCC Retailers Can Cut Payment Costs
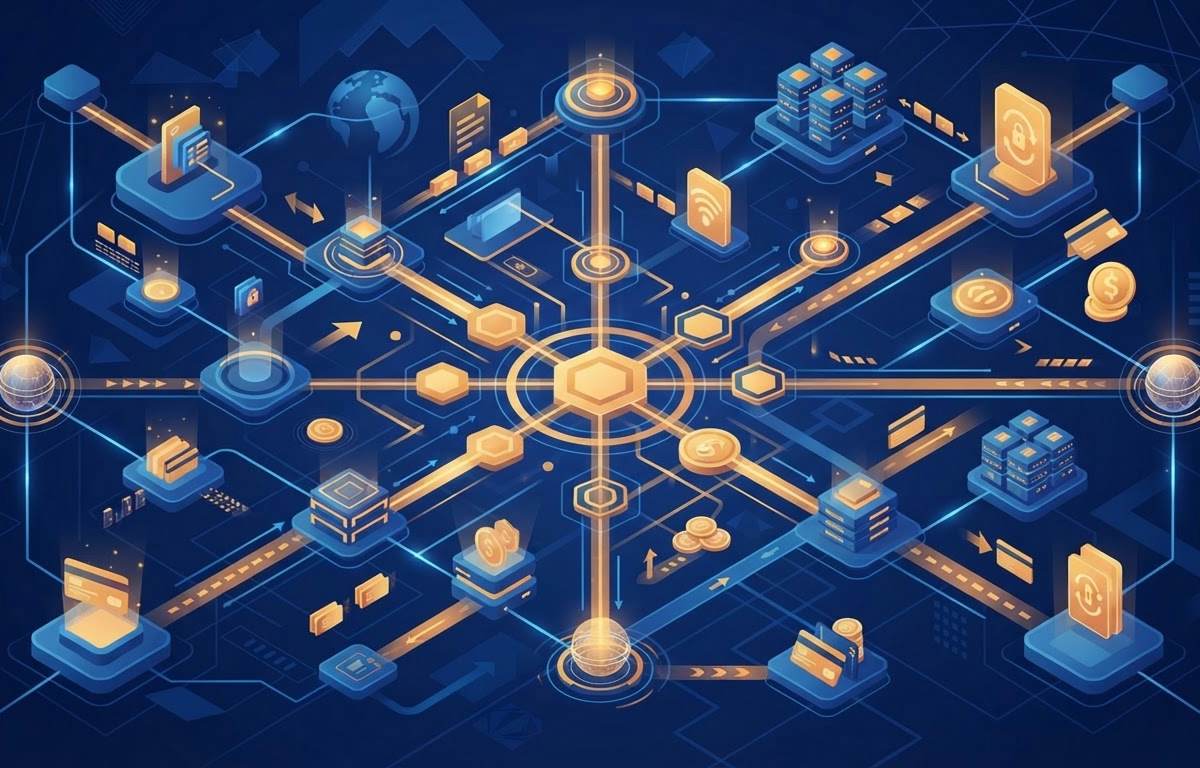
Every time a customer taps a phone or enters card numbers on a checkout page, a complex financial dance takes place in milliseconds. Contrary to popular belief, card networks like Visa and Mastercard do not issue cards, set credit limits, or hold consumer deposits. Instead, they act as high-speed, secure communication backbones that route payment authorizations and settlement data between a merchant's acquiring bank and a customer's card-issuing bank.
Behind every successful checkout lies a four-party system comprising the cardholder, the issuer, the merchant, and the acquirer, orchestrated entirely through the network rail. The network verifies that the card is legitimate, checks fraud parameters, requests authorization from the issuing bank, and returns an approval code to the point of sale. Later that evening or within a settlement window, actual funds are batched and transferred between institutions, leaving the merchant with funds minus an interchange fee and processing margins.
For growing digital enterprises, these mechanics are not academic; they directly dictate profit margins. Processing fees often scale aggressively with transaction volume, and merchants without technical visibility into their payment stacks routinely overpay. Cross-border processing, currency conversion charges, and suboptimal authentication protocols like outdated 3D Secure implementations drive up failed transactions and merchant discount rates, eroding bottom-line revenue on every sale.
In Oman and across the wider Gulf, understanding this architecture is essential for commercial competitiveness. While global schemes dominate international spending, local debit switches such as OmanNet, Saudi Arabia's mada, and Kuwait's KNET offer significantly lower transaction costs and faster domestic settlement. Forward-thinking Omani retailers and e-commerce platforms are increasingly configuring dynamic routing into their checkout engines, automatically funneling domestic debit cards through domestic switches while reserving Visa and Mastercard rails for international or credit transactions.
To capitalize on these dynamics, business owners in the region must treat their digital checkout as an engineering asset rather than an off-the-shelf commodity. Partnering with skilled regional developers to build custom e-commerce integrations, audit gateway transaction reports, and implement smart fallback mechanisms directly protects margins under Oman Vision 2040's burgeoning digital economy. Controlling how transactions travel across global and local rails is one of the most immediate cost-saving levers available to modern Gulf enterprises.